The Psychology of Trading With Money You Don't Have
June 24, 2026 · ~10 min read · by Shivam Kushwaha, HeyArtha founder
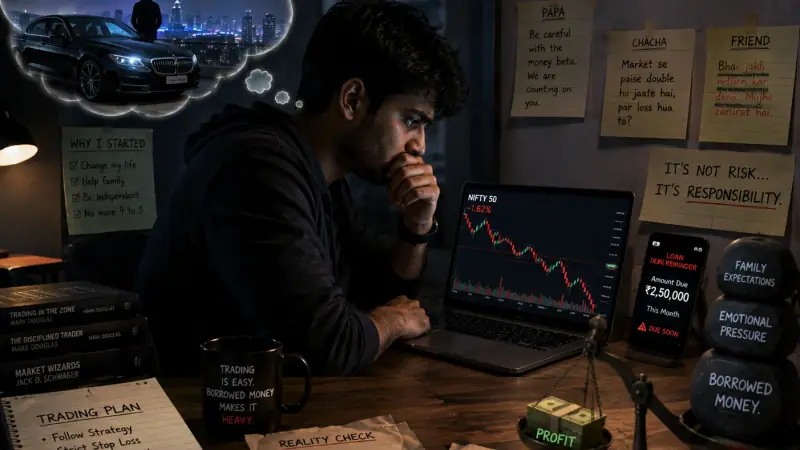
The cash advance took less than two minutes to hit your account. You told yourself it was temporary, a bridge, money you'd put back before the statement even generated, once this next trade came through the way the last few almost did. That was six weeks ago. The credit card bill is sitting unopened in your email now, and the number in your trading app doesn't match the number in your head anymore, because somewhere in there you stopped counting it as debt and started counting it as capital. Nobody in your life knows where any of this money actually came from.
Why Borrowed Money Trades Differently Than Your Own
Here's the mechanism I think is worth naming: many traders say money that isn't really theirs to lose feels less real than money they earned and saved, which can mean the same rupee amount, borrowed instead of owned, produces looser risk decisions, faster escalation, and a harder time stopping, even in traders who are otherwise genuinely careful. It isn't that borrowed money is inherently more dangerous as a number. It's that the psychological brakes that normally slow someone down before a risky trade are weaker when the money in question already feels, in some sense, like someone else's problem to eventually deal with.
That distinction matters because most people who end up here didn't start out reckless. They started out confident, maybe even right about a setup or two, and the borrowing crept in gradually, a cash advance to "just get back to even," a family loan framed as temporary, rather than a single dramatic decision to gamble with money that wasn't theirs. This is my reading, not a finding from the case report.
Why This Is Becoming More Common, Not Less
Mobile trading apps have made the gap between "I want to trade more" and "I am now trading more" close to instant, no paperwork, no waiting period, nothing that gives the decision time to cool before it becomes irreversible. A credit card cash advance or an instant personal loan app can fund a trading account faster than most people can talk themselves out of it, and that speed can do real damage. Picture someone treating a new ₹5 lakh credit limit as an opportunity to jumpstart investing, rather than what it actually is, a debt with interest attached regardless of what the market does next. A Business Standard explainer on investing with a credit card uses a similar example and warns about the high interest and volatility involved.
Clinicians at NIMHANS in Bengaluru have now published a case report on severe, addictive-like stock trading in a 29-year-old employed man, which suggests this is a pattern clinicians take seriously. I could not find a reliable count of how many people are affected, so treat anything that gives a precise number with caution.
What the Behavior Actually Looks Like Up Close
A recently published case report from NIMHANS' SHUT Clinic, which specifically treats technology-related behavioral problems, described a 29-year-old employed man with severe addictive-like stock trading, measured with the Stock Addiction Inventory, a nine-item questionnaire developed in 2016 by Korean researchers, and treated with a multimodal approach. It is one case, so it shows the pattern exists rather than how common it is. Press coverage of the case says the man had borrowed through digital loan apps.
What makes borrowed-money trading specifically dangerous isn't just the debt itself, it's the timeline pressure debt adds on top of ordinary trading stress. A loss funded by savings is painful but bounded, the savings are simply gone. A loss funded by a loan or a credit card keeps compounding on its own schedule, interest accruing whether the market cooperates or not, which adds a second, parallel source of anxiety running underneath every single trade made afterward.
How This Actually Plays Out for Different People
For some traders, this starts with a single cash advance during an unusually confident stretch, intended purely as a short-term boost, and the position works out, reinforcing the idea that borrowing to trade is a reasonable tool rather than a warning sign, right up until a losing stretch turns the same tool into a spiral.
For others, the money isn't borrowed from an institution at all, it's borrowed from people, a parent's fixed deposit "just for a few weeks," a sibling's wedding fund quietly used as bridge capital, framed internally as temporary even when there's no real plan for how or when it gets replaced. This version carries a specific, additional weight, because the debt isn't just financial, it's relational, and the shame of admitting it involves someone else's trust, not just your own risk tolerance.
A third pattern shows up in traders already deep in a losing streak on their own capital, who turn to borrowed money specifically to chase the loss back, treating the fresh capital not as a new, separate decision but as an extension of a bet that already feels unfinished. This is often the fastest-moving version of the pattern, since the psychological state driving it, urgency, desperation, the need to make the loss "not have happened," is already primed before the borrowed money even arrives.
What Actually Helps, Distinct From Willpower Alone
Naming the actual source of the capital honestly, even just to yourself in writing, tends to interrupt the mental relabeling that makes borrowed money feel like ordinary capital. Writing "this is a credit card cash advance at [X]% interest, not savings" before a trade, every single time, keeps the real stakes visible in a way that a rounded number in an app deliberately doesn't.
Separating the debt conversation from the trading conversation is worth doing early and honestly, ideally with whoever the money actually came from, before the gap between what they think happened and what actually happened grows any wider. That conversation is uncomfortable in the short term and considerably less damaging than the one that happens after months of compounding interest and escalating positions.
If the pattern includes preoccupation with the market outside trading hours, chasing losses specifically to make them "not count," or an inability to stop even when you've genuinely decided to, that combination is worth taking to a real mental health professional, not just managing through journaling or willpower. NIMHANS in Bengaluru runs the SHUT clinic for technology-related problems, and the institute's main number is 080-26995000; ask there what the clinic covers. Tele-MANAS, the Ministry of Health's mental health helpline, is also available around the clock at 14416 or 1-800-891-4416, for anyone who needs to talk to someone before deciding what to do next.
What tends not to help is treating the debt as a separate problem to deal with "once the trading turns around." That framing keeps the two problems artificially split in a way that usually just lets both get worse in parallel, since the pressure to recover the debt is often exactly what drives the next reckless trade.
Where Artha Fits In
This is precisely the kind of pattern that's hard to name out loud, because saying "I funded this with a credit card advance and I haven't told my family" can feel less like describing a common pattern and more like confessing something unforgivable. It's very often where hiding losses from the people closest to them and whether their trading has quietly become something closer to compulsion both converge at once.
A Small Thing Worth Saying Honestly
I'm not a trader myself, but I've seen how quickly a number on a screen can stop feeling like money once there's a story attached to how it'll be paid back "eventually." What strikes me most is how ordinary the people affected actually are, not reckless by nature, just caught in a loop that got harder to see clearly the deeper it went, the same way a small trading account's mismatch between rupee-scale hope and percentage-scale reality quietly pulls people toward bigger, riskier bets.
The money was never really borrowed from a bank or a relative alone. Some part of it was borrowed from a future version of you who was going to have to deal with the consequences, and that version rarely gets consulted before the decision gets made.
If the capital in your account right now had to stay exactly as visible as a loan statement, interest rate and all, would you still be trading it the way you are?
Quick answers
Things people usually want to know.
Why does trading with borrowed money feel different from trading my own savings?
Many traders say money that is not fully theirs feels less real, which can loosen the caution that normally slows risky decisions. That is a common description rather than a measured rule, but it is why writing down where the money came from can help.
Is it common for people to trade with credit card cash advances or loans in India?
I could not find a reliable figure for how many people do this. Press reports and clinicians describe borrowing to trade, including through instant loan apps, in the case of the NIMHANS patient. It is risky because interest keeps accruing whatever the market does.
What are the signs that trading has become a compulsive behavior, not just a habit?
Signs people and clinicians describe include preoccupation with the market outside trading hours, chasing losses with bigger trades, sleep disrupted by open positions, and being unable to stop after deciding to. Only a mental health professional can say whether it is compulsive.
Where can I get help for trading addiction in India?
NIMHANS in Bengaluru runs the SHUT clinic (Service for Healthy Use of Technology); the institute's main number is 080-26995000, and it is worth asking what the clinic covers. Tele-MANAS, the Ministry of Health's mental health helpline, takes calls around the clock at 14416 or 1-800-891-4416.
Why do people borrow money from family to trade instead of telling them the truth?
Often because the initial ask feels temporary and manageable, framed as a short-term bridge rather than real risk, and by the time it's clear the money won't be replaced quickly, the shame of the original framing makes honesty feel even harder than it would have at the start.
Is trading with borrowed money always a sign of addiction?
No, not on its own. But it is a warning sign worth taking seriously, especially if it comes with chasing losses, escalating amounts, or difficulty being honest with people close to you about where the money came from.
How does debt from trading affect decision-making differently than a straightforward loss?
Borrowed money keeps accumulating interest on its own timeline regardless of market outcomes, which adds ongoing financial pressure on top of the emotional stress of trading itself, often pushing people toward faster, more desperate decisions to try to outrun the debt.
Should I tell my family if I've borrowed money from them to trade and lost it?
In my view, the earlier, harder conversation is usually less damaging than the one that happens after months of mounting interest and attempts to fix it quietly. It is still your call, and a counsellor can help you plan what to say.
What is the Stock Addiction Inventory?
It is a nine-item self-report questionnaire developed in 2016 by Korean researchers, using a sample of 1,005 traders and investors, to screen for gambling-like problems in financial markets. The NIMHANS case report used it to measure severity. It is a screening tool, not a diagnosis.
Can trading with borrowed money lead to a cycle that's hard to stop on your own?
It can. The pressure to repay the debt often becomes a reason to keep trading rather than stop, turning one decision into an ongoing cycle. If you find you cannot stop even after deciding to, outside support from a mental health professional is worth seeking.
Where can I talk honestly about this without judgment?
Anonymous peer spaces built for trading psychology, like Artha's Traders' Talk room, let you describe the real situation, including where the money came from, with other traders who understand the pull without turning it into criticism or a strategy lecture.
More from HeyArtha
Other things we've been writing about.
Brokerage Charges and Tax on Trading Income in India (2026)
Brokerage is the smallest cost. What STT, GST, stamp duty and DP charges add to a ₹1 lakh delivery trade, and how delivery, intraday and F&O income is taxed.
Budget Day Brain: Why Feb 1 Turns Disciplined Traders Reckless
Union Budget day making your trading brain go haywire? Here's an honest look at the psychology of high-volatility event days, no calls, just the mindset.
What the CFA Charter Actually Gets You in India: A Realistic View
₹32.4 lakh average for recent charterholders, ₹66.6 lakh overall. Here's what those numbers actually mean, and what they don't.