
FRM vs Actuarial Science: Two Roads Into Risk (India)
August 15, 2026 · 10 min read · by Shivam Kushwaha, HeyArtha founder
CA Intermediate MCQ Test Series
60 timed case-scenario tests across Corporate & Other Laws (15 tests) and Taxation (45 tests). 30 marks, 2 marks per question, step-by-step statutory citations, no negative marking, and performance certificates.
Both get called "risk careers" in casual conversation, which makes them sound almost interchangeable from the outside. They aren't. Someone drawn to "working in risk" without more specificity is often actually torn between two genuinely different professional worlds that happen to share a word in their name.
The overlap and the difference are both real: some underlying topics in actuarial science and FRM are similar, but the focus differs. In one common view, actuarial training is more extensive and better suited to insurance work, while FRM concentrates on a narrower, more immediately applicable set of risk-management concepts and methods.
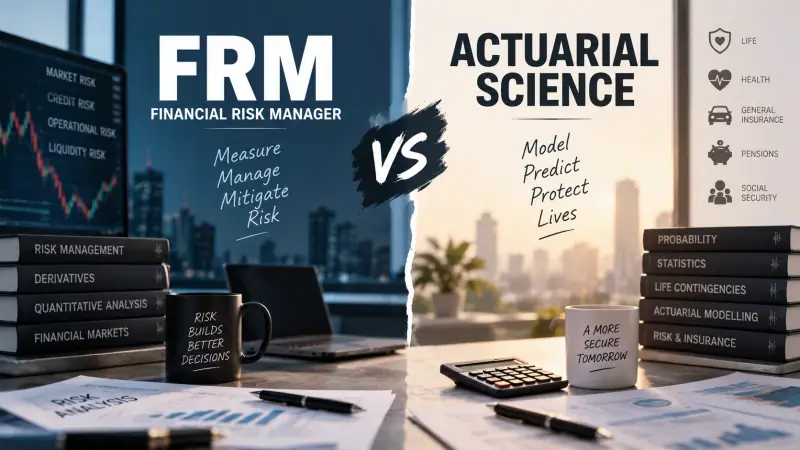
FRM, through GARP, is a two-part credential built around market, credit, and operational risk, primarily relevant to banks, NBFCs, and broader financial-sector risk functions. Actuarial Science, through IAI, is a staged, multi-year credential built around insurance and pension risk, such as mortality, morbidity, and long-term liability modeling. Both genuinely involve quantitative risk work. Which specific industry that risk work happens inside, banking and finance broadly versus insurance and pensions specifically, is the real distinguishing question.
The actual numbers, side by side
| FRM (GARP) | Actuarial Science (IAI) | |
|---|---|---|
| Governing body | Global Association of Risk Professionals | Institute of Actuaries of India |
| Structure | 2 parts, with 100 and 80 multiple-choice questions respectively, per GARP | ACET entrance test, followed by IAI's staged professional exams; check IAI's exam structure page for the current stages |
| Core focus | Market risk, credit risk, operational risk, quantitative risk models for banking and financial institutions | Insurance and pension risk modeling, mortality and morbidity analysis, long-term liability quantification |
| Typical duration | Varies with attempts; GARP allows four years from passing Part I to pass Part II and requires two years of relevant work experience | Highly variable and typically several years |
| Reported total cost | Check GARP's fees and payments page for current fees | Costs accumulate across ACET and multiple staged exams; check IAI for current fees |
| Pass rates | GARP's exam page reports 47 percent for Part I and 50 percent for Part II in the November 2025 window | No single headline figure is cited here; check IAI's published results |
| Primary Indian industry | Banks, NBFCs, and broader financial-sector risk, treasury, and compliance functions | Historically concentrated largely within India's insurance industry |
| Regulatory driver | Basel III and RBI-driven risk management requirements at Indian banks and NBFCs | India's insurance regulatory framework and the specific actuarial certification requirements insurers must meet |
This guide does not quote salary figures, because those circulating online conflict substantially. What is more reliably true, structurally, is that FRM's Indian relevance spans a broader financial-sector base (banks, NBFCs, and related risk functions), while actuarial science's Indian relevance concentrates heavily within one specific industry, insurance.
What FRM is actually for
FRM exists specifically to build and certify risk-management competence for the banking and financial sector: market risk, credit risk, operational risk, and the quantitative models underlying all three. GARP's two-part structure, more compact than actuarial science's staged sequence, reflects a credential built for people already working, or aiming to work, inside bank or NBFC risk functions specifically, rather than a from-scratch professional qualification pathway the way actuarial science is structured.
The India-specific case for FRM is often linked to Basel III implementation and RBI's regulatory emphasis on risk management at Indian banks. Bank staff looking for a credential that deepens risk-management specialisation are a natural audience for FRM.
The real limitation is that FRM's relevance is concentrated within banking, NBFCs, and broader financial-sector risk work. It doesn't touch insurance-specific risk modeling, mortality and morbidity analysis, or the kind of long-term liability quantification actuarial training goes deep into. Someone whose actual interest is insurance industry risk work specifically will find FRM's curriculum, while genuinely rigorous within its own domain, doesn't build the specific technical depth insurance risk roles require.
What Actuarial Science is actually for
Actuarial Science exists to train and certify people specifically for insurance and pension risk quantification, a technically demanding field requiring probability, statistics, and mortality or morbidity modeling that goes considerably deeper into pure quantitative theory than FRM's more applied, banking-oriented curriculum. Actuarial training is generally considered more extensive and well suited to the insurance industry, in a way FRM's more concentrated, immediately applicable structure isn't built for.
The real strength here is depth within a genuinely scarce specialism. Because full qualification requires clearing a demanding, staged sequence over several years, those who complete it hold deep expertise within India's insurance industry, which has an ongoing regulatory need for qualified actuaries.
The real limitation, and one worth being honest about specifically for India, is how narrow that application currently is. In India, actuaries have historically been concentrated largely in the insurance industry, unlike some other markets where actuarial-trained professionals work more broadly in risk functions. Someone completing the full actuarial sequence gains real depth, but within a considerably narrower current Indian job market than FRM's banking-and-NBFC-spanning relevance offers.
Where people get this decision wrong
The most common mistake is treating "risk career" as a single, undifferentiated goal and picking whichever credential comes up first in a search, without recognising how different banking risk and insurance risk actually are as professional domains. Someone who wants to work specifically in bank or NBFC risk, credit risk assessment, market risk modeling, operational risk frameworks, gains little from actuarial science's insurance-specific technical depth, even though both credentials get labeled "risk management" in casual conversation.
The reverse mistake happens with people drawn to actuarial science specifically because of its reputation for high scarcity-driven pay, without checking whether insurance-specific risk modeling, as opposed to banking or broader financial risk work, genuinely interests them, and without accounting for how narrow that career currently is within the Indian market specifically. Someone who completes the long, demanding actuarial sequence only to discover their real interest was closer to FRM's banking-risk domain has spent years building deep expertise in the wrong specific industry.
A third pattern involves underestimating how much faster and more immediately applicable FRM is for someone already working in banking or NBFC risk functions, choosing actuarial science instead purely because it sounds more prestigious or more mathematically rigorous, without weighing the real trade-off in timeline. FRM's two-part structure can deepen an existing banking risk career faster than actuarial science's longer staged path, and for someone already inside a bank or NBFC risk role, that speed genuinely matters.
A fourth pattern shows up in people assuming the genuine content overlap between the two, both involve real quantitative risk modeling, means either credential prepares you reasonably well for the other's specific industry. It doesn't, in practice. FRM's models are built around market and credit risk in banking contexts; actuarial models are built around mortality, morbidity, and long-term insurance liabilities. The underlying mathematical instincts transfer somewhat, but the specific technical content and industry relationships genuinely don't overlap as much as the shared word "risk" suggests.
The actual decision
The real question isn't which credential involves more rigorous quantitative work, since both genuinely do, in different technical directions. It's whether your actual interest and career direction point toward banking and financial-sector risk, market, credit, operational, in which case FRM's faster, more immediately applicable structure fits that goal directly, or toward insurance and pension risk specifically, mortality, morbidity, long-term liability modeling, in which case actuarial science's deeper, more specialised, and considerably longer path fits that goal instead.
If you're already working in or targeting a bank or NBFC risk role, FRM is very often the more direct, faster-to-complete fit, matching the demand from bank risk functions. If your genuine pull is specifically toward insurance industry risk work, and you're comfortable with a considerably longer timeline and a currently narrower Indian job market concentrated in that one industry, actuarial science is built specifically for that interest in a way FRM's banking-oriented curriculum isn't.
Where Artha fits
"Risk career" gets treated as one undifferentiated goal far too often, when banking risk and insurance risk are genuinely different professional worlds that happen to share a word, and nobody neutral is usually around to point that out clearly before someone commits years to the wrong specific industry.
I'm not selling FRM prep or actuarial exam coaching. I just wanted this comparison written honestly, including being upfront that this is a genuinely lower-volume, less-covered comparison than some others, precisely because it's under-served rather than because the underlying confusion isn't real.
Banking risk or insurance risk, genuinely different worlds
FRM points toward banking, NBFC, and broader financial-sector risk work, faster to complete and increasingly in demand given India's Basel III-driven regulatory push. Actuarial Science points toward insurance and pension risk specifically, deeper and considerably longer to fully qualify in, currently concentrated narrowly within India's insurance industry. Both are genuinely "risk careers." They just aren't the same risk career, whatever the shared label suggests.
Is your actual pull toward banking and financial-sector risk, or toward insurance and pension risk specifically, because those are genuinely different industries wearing the same word?
Quick answers
Things people usually want to know.
Is FRM the same as Actuarial Science?
No. FRM, from GARP, focuses on market, credit and operational risk for banks and financial institutions. Actuarial Science, through the Institute of Actuaries of India, focuses on insurance and pension risk such as mortality and long-term liabilities.
Which is better for a risk career in India, FRM or actuarial science?
It depends on the industry you want. FRM points to banks, NBFCs and financial-sector risk functions, while actuarial science points mainly to insurance. Pick the industry first, then the credential.
How many questions are in the FRM exam?
According to GARP, FRM Part I has 100 multiple-choice questions and Part II has 80, each over four hours. Check GARP's program exams page for the current format.
What are recent FRM pass rates?
GARP's exam page reports 47 per cent for Part I and 50 per cent for Part II in November 2025. Pass rates change by window, so check GARP for the latest.
How long does FRM take?
It depends on your pacing and attempts. GARP allows four years from passing Part I to pass Part II, and requires two years of relevant work experience for certification, which can be completed before or after the exams.
What is the ACET exam?
ACET is the entrance test of the Institute of Actuaries of India. Passing it makes a candidate eligible to apply for student membership but is not itself a professional actuarial qualification. Check IAI for the current pattern and dates.
How long does it take to become an actuary in India?
It takes several years and varies widely with attempts, because the exams are staged. Check the Institute of Actuaries of India's exam structure page for the current stages and requirements.
Can an actuary work outside insurance in India?
Historically most Indian actuaries have worked in insurance, though some markets use actuarial training more broadly in risk functions. Check current job postings in your target sector before assuming opportunities.
Does FRM help with insurance risk roles?
Not directly. FRM covers market, credit and operational risk in banking contexts, and does not go into mortality, morbidity or long-term insurance liabilities in the way actuarial training does.
Can I do both FRM and actuarial science?
It is possible, but the two lead to different industries and the actuarial path is long. Have a clear target role in mind before committing years to both.
More from HeyArtha
Other things we've been writing about.
Passed All the Exams, Still Not Qualified: The ACCA/CFA Limbo
You cleared every paper. You're still not a member or a charterholder. Here's why that gap exists, and what to actually do about it.
ACCA Exemptions After CA or B.Com: What You Actually Skip
A CA can skip up to 9 of 13 ACCA papers. A B.Com grad usually skips 3-4. Here's exactly what you keep, what you still sit, and what it costs.
ACCA Job Prospects in India: Beyond the Only Useful Abroad Myth
ACCA is not only for people leaving India. Here's the honest picture of what it opens up domestically, and the one thing it cannot do.