
Broke on a Good Salary: The Anxiety Nobody Admits
July 9, 2026 · 10 min read · by Shivam Kushwaha, HeyArtha founder
CA Intermediate MCQ Test Series
60 timed case-scenario tests across Corporate & Other Laws (15 tests) and Taxation (45 tests). 30 marks, 2 marks per question, step-by-step statutory citations, no negative marking, and performance certificates.
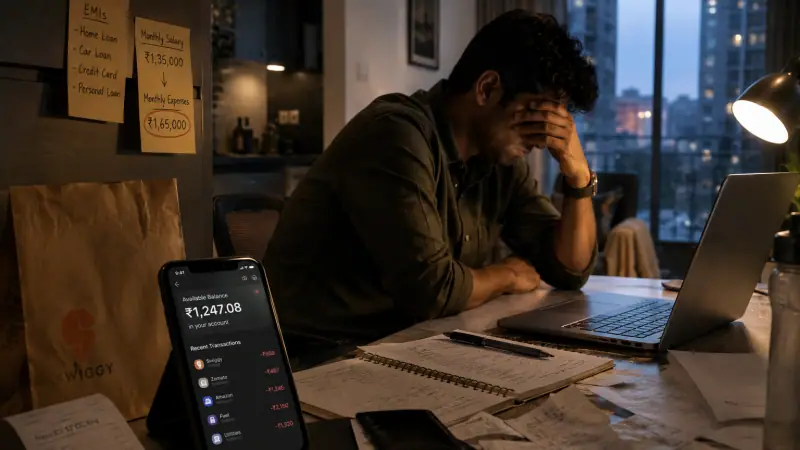
Your salary slip says ₹14 lakh a year. A number that would have sounded unreal to you five years ago. It's the 28th of the month, and your account has ₹6,200 in it, rent already paid, card bill already due, nothing left over except the quiet, familiar dread of doing this exact math again next month. Everyone assumes you're doing well. On paper, you are, the exact gap that shows up whenever a good-sounding number gets measured against someone else's better one, a figure that still somehow doesn't feel like enough once it meets the real cost of an actual life.
Why "Good Salary" Doesn't Always Mean Financially Secure
Feeling broke on a salary that objectively looks good is a genuinely common experience, not a sign you're managing money unusually badly. Expenses tend to rise in step with income almost automatically, a pattern with a real name, lifestyle inflation, and it happens quietly enough that most people don't notice their spending has scaled up until they're staring at the same thin cushion they had three raises ago.
The mismatch is sharpest in metro cities specifically. Rent alone can consume a huge share of a salary that would stretch comfortably in a smaller town, and once you add transport, subscriptions, eating out, the small daily costs of city life, the gap between "sounds like a lot" and "actually available at month's end" grows wider than most people expect before they're living it firsthand.
There's also a specific confusion that comes from comparing your current number to your own past self rather than to your current cost of living. ₹14 lakh sounds enormous next to the ₹4 lakh you started at. It doesn't sound nearly as large next to Mumbai or Bengaluru rent, a rising grocery bill, and the dozen small recurring payments that accumulate almost invisibly once a stable income makes them easy to say yes to.
The Data Behind the Feeling
This isn't just an individual perception problem. A Business Standard report on a survey by Marcellus Investment Managers and Dun & Bradstreet India found that about 43% of high-income respondents were saving less than 20% of their post-tax income. The survey covered 465 respondents, individuals over 30 with post-tax incomes above ₹20 lakh a year. These aren't people mismanaging modest salaries. These are high earners, by any conventional measure, still finding it difficult to save at a rate most financial guidance would consider healthy.
The Business Standard report presents lifestyle inflation as a key reason, with premium education, better real estate and upgraded travel rising in step with income until spending nearly matches earning. That is the report's explanation, not something the survey measured directly. It is difficult to step off, not because of weak willpower, but because each individual upgrade feels reasonable and earned in the moment it happens, and it's only the cumulative effect, viewed months later, that reveals the pattern.
There's a cultural layer specific to India worth naming too. Family financial contributions, siblings' education, parents' medical costs, wedding expenses, aren't optional extras for a lot of earners, they're expected, genuinely meaningful uses of money that come from love rather than obligation, and they meaningfully shrink what's actually left over, in a way that a salary number alone never captures.
Why This Feels Worse Than It Should
Part of the discomfort is that "broke on a good salary" doesn't sound like a real problem from outside it. Complaining about money on ₹14 lakh a year, next to someone earning a fraction of that, can feel almost obscene to say out loud, which means a lot of people carry the actual anxiety silently, unable to talk about it honestly with almost anyone in their life without it sounding like ingratitude.
There's also a comparison trap that runs constantly in the background. Social media makes other people's spending, the trip, the upgrade, the new phone, extremely visible, while making their actual financial stress almost entirely invisible. You end up comparing your real, felt financial anxiety against everyone else's curated highlight reel, a comparison that's structurally unfair before it even starts, the same distorted math that fuels feeling like everyone your age is doing better than you more broadly, not just financially.
It doesn't help that leaving a stable path to build something of your own, or staying in one out of obligation, both come with their own version of this exact anxiety. Someone who quit a secure job to build a startup carries a more visible, more openly discussed version of financial precarity. The person on a solid, "good" salary who's still quietly broke every month carries something quieter, harder to name, and, precisely because it doesn't look like a crisis from outside, much easier to keep carrying alone.
What Actually Helps
Tracking where the money is actually going, not from memory but from real numbers over a full month, tends to surface the gap between perceived and actual spending faster than any general resolution to "save more" ever does. Lifestyle inflation is sneaky precisely because it happens in small, individually reasonable increments, and only a real, itemized look tends to make the cumulative pattern visible.
Automating savings before spending, rather than trying to save whatever's left at the end of the month, changes the entire dynamic, since "whatever's left" has a way of quietly shrinking to match whatever's spent first. A fixed amount moved out immediately, before it has the chance to feel spendable, tends to actually stick in a way manual, end-of-month saving rarely does.
It helps to separate genuine financial anxiety from status-driven spending as honestly as you can. Some expenses are real, necessary, or deeply meaningful, family support, a rent you can't easily reduce, and some are quieter upgrades that crept in because they felt normal at your current income level rather than because they were actually chosen deliberately. Neither category is wrong to spend on. Knowing which is which changes how much control the whole situation actually feels like it has.
If comparing your own numbers to a viral headline figure, like the ones that circulate around CA placements or any other profession's best-case story, is part of what's driving the anxiety, it's worth remembering that most of those numbers represent outliers, not the actual median experience most people are living, including plenty of people who look, from outside, like they're doing exactly fine.
What I've Noticed Building This
Between CA prep and self-funding Artha from trading, I know a version of this tension myself, watching money move between what's needed for the business and what's actually left over personally. What I've noticed, both in that and in reading conversations across Artha, is how rarely people actually talk about this honestly, even with close friends, because the number itself sounds like it should have solved the problem, and admitting it hasn't feels like it's contradicting your own good fortune.
A good salary and a secure feeling are not automatically the same thing, even though the number on the offer letter suggested they would be. What's one expense you're currently paying that you'd genuinely reconsider, if you let yourself actually look at it honestly?
Quick answers
Things people usually want to know.
Is it normal to feel broke even when earning a good salary?
Yes, it is a common experience. A survey by Marcellus and Dun & Bradstreet India found that about 43% of respondents over 30 with post-tax incomes above ₹20 lakh a year were saving less than 20% of their post-tax income. Business Standard linked this to lifestyle inflation.
What is lifestyle inflation and why does it happen?
Lifestyle inflation is the tendency for spending to rise as income rises, often through small upgrades that each feel reasonable. It happens gradually, so most people notice only when they compare their savings against their income directly.
Why does a good salary feel insufficient in metro cities?
Rent and living costs in large cities take a bigger share of income than in a smaller town, which narrows the gap between earnings and expenses. A number that sounds large on paper often stretches less once those costs are included.
How can I stop lifestyle inflation from eating my raise?
Move a fixed savings amount out right after each paycheck, before you spend, instead of saving what is left at month end. Tracking actual monthly expenses also shows which increases were deliberate and which crept in.
Is it wrong to feel financially stressed when I earn more than most people around me?
No. Financial stress is not decided only by the size of the salary. Fixed costs, family support and loans matter as much, and comparing yourself to others hides most of that. Talking about it honestly with someone you trust usually helps.
How much of my salary should I save?
There is no single rule. The survey report quoted an advisor suggesting that people earning above ₹20 lakh aim for 30 to 40 per cent of post-tax income. Others suggest different targets, so pick a rate that covers your obligations and goals.
How do I find where my money is going?
Track every expense for a full month from your bank and card statements, not from memory, and group them into fixed costs, family support and discretionary spending. The totals usually show the gap between perceived and actual spending.
Should family financial support count as a spending problem?
Not necessarily. Support for parents, siblings' education or medical costs is often a deliberate choice. It is worth listing separately so you can see what is left, and plan savings around it rather than feeling you are failing.
More from HeyArtha
Other things we've been writing about.
Passed All the Exams, Still Not Qualified: The ACCA/CFA Limbo
You cleared every paper. You're still not a member or a charterholder. Here's why that gap exists, and what to actually do about it.
ACCA Exemptions After CA or B.Com: What You Actually Skip
A CA can skip up to 9 of 13 ACCA papers. A B.Com grad usually skips 3-4. Here's exactly what you keep, what you still sit, and what it costs.
ACCA Job Prospects in India: Beyond the Only Useful Abroad Myth
ACCA is not only for people leaving India. Here's the honest picture of what it opens up domestically, and the one thing it cannot do.